Tax planning is one of the most practical ways for individuals in India to keep more of what they earn while building long-term financial security. The Income Tax Act provides several legal deductions and investment options that reduce taxable income. For beginners, understanding the main sections and instruments can turn tax season from a source of stress into an opportunity for disciplined saving and wealth creation.
Choosing Between the Old and New Tax Regimes
India currently offers two tax regimes. The new tax regime is the default and features lower slab rates along with a standard deduction of ₹75,000 for salaried individuals. Under this regime, most traditional deductions such as those under Section 80C and 80D are not available. Income up to a certain threshold can attract zero tax due to the rebate under Section 87A, making the new regime attractive for those with limited investments or deductions.
The old tax regime allows a wide range of deductions and exemptions. It suits taxpayers who invest regularly in eligible instruments, pay health insurance premiums, claim house rent allowance, or service a home loan. The choice depends on total income, available deductions, and financial goals. Calculating tax liability under both regimes each year helps determine which option yields the lower outflow.
Section 80C: The Core Tax-Saving Limit
Section 80C remains the most widely used provision under the old regime. It allows a deduction of up to ₹1.5 lakh per financial year on a combination of eligible investments and expenses. Popular options include Equity Linked Savings Schemes, Public Provident Fund, Employee Provident Fund, life insurance premiums, National Savings Certificates, five-year tax-saving fixed deposits, tuition fees for children, and principal repayment on home loans.
Because the limit is collective, spreading investments across instruments with different risk levels, lock-in periods and return profiles creates balance. Exceeding ₹1.5 lakh does not generate additional deduction under this section.
Equity Linked Savings Schemes for Growth Potential
Equity Linked Savings Schemes are mutual funds that invest primarily in equities and come with a mandatory three-year lock-in, the shortest among Section 80C options. They offer the possibility of higher long-term returns linked to market performance, though they carry equity-related risk. For investors with a longer time horizon and the ability to tolerate short-term volatility, these schemes combine tax benefits with wealth-creation potential. Gains beyond a specified annual threshold are subject to long-term capital gains tax.
Public Provident Fund for Safety and Tax-Free Returns
The Public Provident Fund is a government-backed scheme with a 15-year tenure. Contributions qualify for Section 80C deduction, and both interest and maturity proceeds are completely tax-free, giving it Exempt-Exempt-Exempt status. The interest rate is notified by the government and revised periodically. Partial withdrawals and loans are permitted under prescribed conditions after a minimum period. It suits conservative investors seeking safety and long-term compounding.
National Pension System for Additional Deduction
The National Pension System provides an extra deduction of up to ₹50,000 under Section 80CCD(1B) over and above the Section 80C limit. Contributions can be allocated across equity, corporate bonds and government securities. The scheme is designed for retirement and remains locked until the age of 60, with partial withdrawal rules applying under specific circumstances. At maturity, a portion can be taken as a lump sum while the balance is used to purchase an annuity. It appeals to those focused on retirement planning who want both tax relief and market-linked growth.
Health Insurance Under Section 80D
Section 80D allows deduction for health insurance premiums paid for self, spouse, children and parents. The limits are higher when covering senior citizens. This deduction not only reduces tax but also encourages adequate medical cover for the family. Premiums must generally be paid through non-cash modes to qualify.
Home Loan Benefits and Other Deductions
Interest paid on a home loan for a self-occupied property qualifies for deduction up to ₹2 lakh under Section 24(b) in the old regime. Principal repayment falls under the Section 80C limit. House Rent Allowance exemption is available to salaried employees living in rented accommodation, calculated according to specific rules based on salary, rent paid and city of residence. Education loan interest can be claimed without an upper limit for a defined period under the relevant section. Donations to approved funds and institutions may also qualify for deduction under Section 80G.
Building a Balanced Approach for Beginners
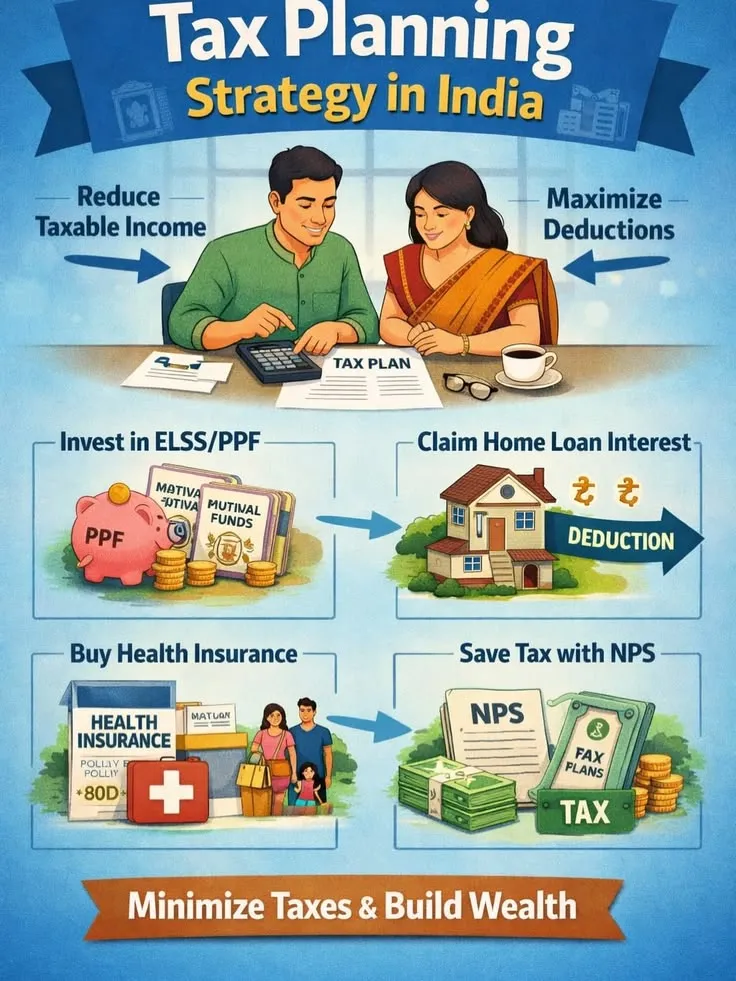
A practical starting strategy for many beginners under the old regime is to combine instruments that match different needs. A portion can go into safer options such as the Public Provident Fund for stability, another into Equity Linked Savings Schemes for growth, and an additional amount into the National Pension System for the extra deduction and retirement focus. Health insurance premiums should be prioritised for both protection and tax benefit.
Timing matters. Investments must be completed before the end of the financial year to claim the deduction for that year. Starting early in the year or through systematic investment plans spreads the outlay and reduces last-minute pressure.
Aligning Tax Saving with Financial Goals
Tax-saving instruments work best when chosen according to personal goals, risk tolerance and liquidity needs rather than solely for the deduction. Short lock-in periods suit those who may need funds sooner, while longer-term schemes support retirement or children’s education. Reviewing the portfolio periodically and recalculating tax liability under both regimes ensures the approach remains optimal as income and circumstances change.
Understanding these options allows beginners to reduce tax legally while building habits of regular saving and investing. The combination of lower tax outflow and growing assets forms a stronger foundation for long-term financial well-being. Consistent, informed decisions each year turn tax planning into a powerful tool for smarter financial management.
Read more – Suvicharsathi.com